
Buying a home creates long-term financial responsibilities. Alongside mortgage repayments, homeowners must manage household bills, maintenance, insurance and other living costs. An unexpected illness, injury or death can place additional pressure on a household, particularly when its income is needed to maintain mortgage payments.
Mortgage protection and life insurance are two ways people may plan for these risks. However, policies differ considerably, and no single product is suitable for every household. Understanding the available options, their limitations and the circumstances in which they pay out can help homeowners make better-informed decisions.
Why Think About Protection When Taking Out a Mortgage?
A mortgage is a long-term commitment, but household circumstances can change. A person who can comfortably afford repayments today may face financial difficulty after losing a partner’s income, becoming unable to work or experiencing a serious illness.
Protection planning starts by identifying which risks would have the greatest financial consequences.
For a household with children, the death of a main earner could leave the surviving family responsible for the mortgage and everyday expenses. For a self-employed person, illness could interrupt income without the benefit of an employer’s sick-pay arrangement.
Other households may already have substantial savings, workplace benefits or alternative sources of income. These factors influence how much protection is needed.
The purpose is not to buy every available policy. It is to understand the financial risks and decide whether insurance offers appropriate value for the circumstances.
What Is Life Insurance?
Life insurance generally pays a benefit if the insured person dies during the period covered by the policy, subject to its terms and exclusions.
The benefit can help surviving family members repay a mortgage, meet household expenses or maintain financial stability. The appropriate level of cover depends on the outstanding mortgage, other debts, dependants, savings and any existing insurance.
There are several policy structures. Some provide level cover, where the insured amount remains constant during the term. Others provide decreasing cover, where the benefit reduces over time. Decreasing-term policies are sometimes considered for repayment mortgages because the outstanding balance is expected to fall.
However, the reduction in the insured amount may not exactly match the mortgage balance. The policy terms, interest-rate assumptions and mortgage structure should be reviewed carefully.
A joint-life policy may cover two people, but many such policies pay out only once, on the first death. That can leave the surviving partner without the same policy protection. The details depend on the contract.
What Is Income Protection Insurance?
Income protection is designed to replace part of an insured person’s income if illness or injury prevents them from working, subject to the policy’s definition of incapacity and other conditions.
Policies commonly have a waiting period before benefits begin. The length of that period can affect the premium, so it should be considered alongside any employer sick pay, savings or other income available.
The benefit may be paid for a specified period or until the policyholder returns to work or reaches the end of the policy term, depending on the policy selected.
Read the definition of incapacity carefully. Some policies assess whether you can perform your own occupation, while others may use a different test. Pre-existing medical conditions, exclusions and limits can also affect eligibility and claims.
Income protection is not identical to critical illness cover. Income protection generally addresses an inability to work because of illness or injury, while critical illness insurance usually pays a lump sum if the insured person meets the policy’s definition of a covered condition.
What Is Critical Illness Cover?
Critical illness cover typically pays a lump sum if the policyholder is diagnosed with a condition that meets the policy’s definitions.
The money may help cover mortgage payments, treatment-related expenses, household bills or other costs during a difficult period.
Not every serious illness automatically qualifies for a payout. Policies list covered conditions and set specific definitions and severity requirements. Some conditions may be excluded, and pre-existing circumstances can affect the cover available.
Before buying a policy, review the full list of covered conditions, exclusions, survival periods if applicable, waiting periods and claim requirements.
It is important to understand that a policy pays according to its contract, not simply because a person experiences a medical problem.
How Much Cover Do You Need?
The right level of protection depends on your financial responsibilities.
Start by listing the mortgage balance, other debts, essential household expenditure and any dependants who rely on your income. Then consider savings, workplace death-in-service benefits, sick pay, existing insurance and the income available from other household members.
For life insurance, ask whether the intended benefit should repay the mortgage in full, cover a proportion of the balance or provide a separate sum for family expenses.
For income protection, estimate the amount needed to cover essential costs during an interruption to earnings. Check whether the policy’s maximum benefit is based on your income and whether other payments reduce the amount payable.
Avoid assuming that the mortgage balance alone determines the right amount of cover. A household may need funds for living expenses as well as mortgage repayments.
Compare Cost, Exclusions and Flexibility
Insurance premiums depend on factors such as age, health, occupation, smoking status, the amount of cover, policy term and insurer underwriting.
A low premium does not automatically indicate good value. Compare the coverage, exclusions, claim definitions, benefit periods and conditions under which the policy can be cancelled or changed.
Check whether premiums are guaranteed or reviewable. Understand what happens if you miss payments and whether the policy remains suitable if you move home, change jobs or repay the mortgage early.
Some policies are linked to a mortgage, while others are arranged separately. A policy should be assessed on its own terms rather than assumed to be appropriate simply because it is offered during a mortgage application.
Do not conceal relevant information when applying for insurance. Inaccurate or incomplete disclosures can affect a claim, depending on the circumstances and applicable law.
Book an appointment now.
Mortgage Protection Is Not the Same as Buildings Insurance
Buildings insurance covers certain risks affecting the physical property, subject to the policy terms. Life insurance and income protection address different risks associated with death or the loss of earnings.
A lender may require appropriate buildings insurance under the mortgage terms, but life insurance is not universally mandatory for every residential mortgage.
Homeowners should distinguish between lender requirements, contractual obligations and optional products intended to provide financial protection.
If an adviser recommends insurance, ask why it is appropriate, what alternatives exist, how much it costs and how the adviser is remunerated. Make sure you understand the policy before accepting it.
Consider Your Circumstances as They Change
Protection needs can change after marriage, the birth of a child, a change in employment, a new mortgage or a substantial increase in household income.
Review existing policies when your circumstances change. Check that the benefit amount, term and beneficiaries still reflect your needs.
A policy arranged years ago may no longer provide sufficient cover, while a household with fewer financial commitments may need a different level of protection. Any replacement should be assessed carefully because new cover may have different underwriting requirements, exclusions or costs.
Avoid cancelling an existing policy before confirming that replacement cover is in place and suitable.
Getting Professional Guidance
A qualified protection adviser can help compare products and explain their terms. The adviser should establish your needs and circumstances before recommending a policy.
Prestige Mortgage Solutions Ltd advertises insurance and protection-related services alongside mortgage advice. Its website provides further information about the services it offers.
Before proceeding, confirm which protection products the firm can advise on, whether it charges a fee, how it is remunerated and which regulatory permissions apply.
You can also consult the MoneyHelper website for general information about insurance and financial planning.
Final Thoughts
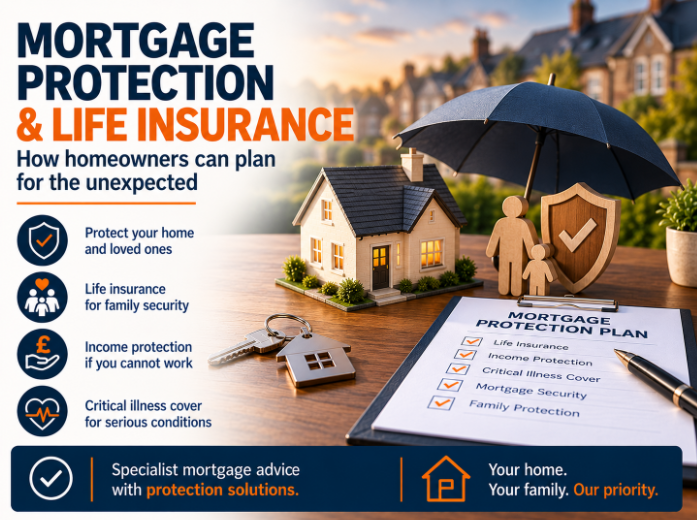
Mortgage protection is about preparing for financial risks that could affect a household’s ability to maintain its standard of living. Life insurance, income protection and critical illness cover address different needs, and their suitability depends on personal circumstances and the policy terms.
The best starting point is to review your mortgage, income, savings, dependants and existing workplace benefits. Compare policies carefully, understand their exclusions and seek appropriate advice before committing to a long-term premium.
Good protection planning should provide a clear purpose and a manageable cost, rather than leaving you paying for cover that does not meet your needs.
This article is for general information only and does not constitute insurance, mortgage, legal or financial advice. Insurance eligibility, exclusions and benefits depend on the individual policy and underwriting decision. Always read the policy documents and obtain advice appropriate to your circumstances.

