

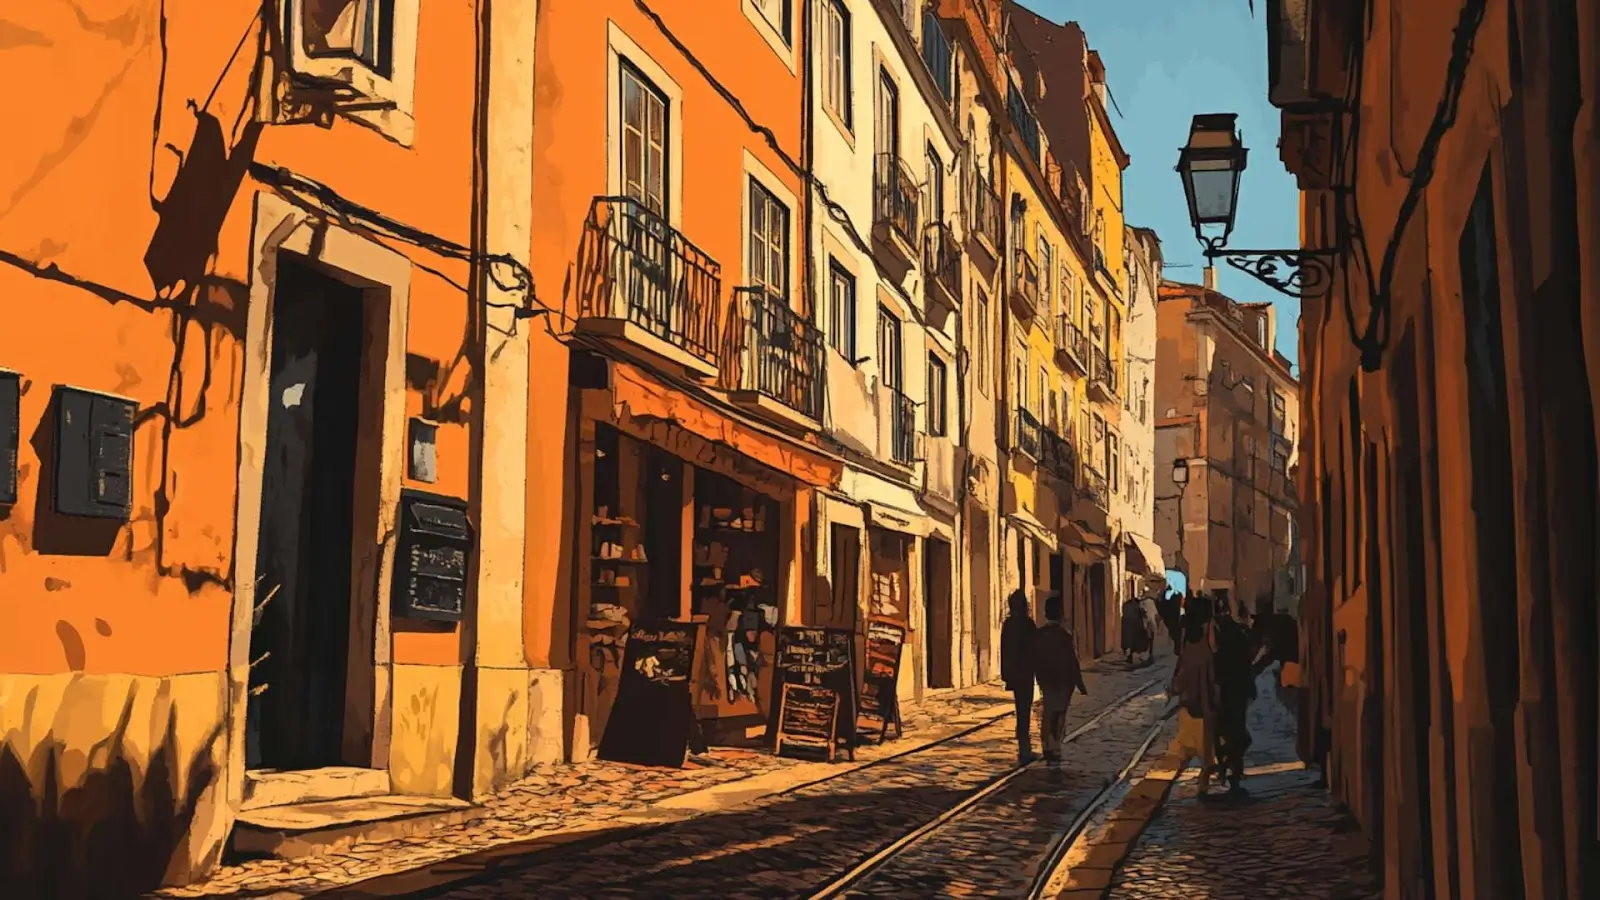
Street retail, which refers to ground-floor retail spaces with direct street access, is becoming a defining segment within Portugal’s commercial real estate landscape. Unlike units in malls or retail parks, these properties are embedded within city life, often located in high-traffic areas such as Lisbon’s Avenida da Liberdade or Porto’s Rua de Santa Catarina. They accommodate a diverse mix of tenants, including cafes, fashion stores, pharmacies, and lifestyle operators.
As the commercial property market evolves, street retail has emerged as a resilient and attractive investment. This article explores the structural factors driving investor interest, key performance indicators, and the outlook for retail assets in Portugal’s urban cores.
Why Street Retail Is Gaining Ground
Several macro trends have reignited interest in this asset class:
- Post-COVID consumer behavior favors local, walkable, and experiential retail over destination shopping.
- Tourism recovery and the growth of digital nomads have increased foot traffic in urban centers.
- Municipal regeneration programs are revitalizing city centers, enhancing the appeal of visible, street-level units.
- Investor appetite for inflation-hedged assets with stable, long-term rental income has grown.
In 2024, retail investment in Portugal reached €1.2 billion, with high-street retail comprising a growing share. Lisbon and Porto remain the key hotspots, but secondary cities like Braga, Coimbra, and Faro are seeing increased activity as well.
What Sets Street Retail Apart?
Street retail differs from other retail formats in both function and value proposition:
| Feature | Street Retail | Shopping Centers | Retail Parks |
| Location | Embedded in city centers | Suburban/destination-based | On outskirts |
| Consumer Flow | Organic foot traffic | Destination-driven | Vehicle-access reliant |
| Tenant Mix | Independent/local + flagship | Chains + anchors | Large-format retailers |
| Experience | Lifestyle-driven, urban | Controlled environment | Transactional use |
Street retail supports a wide range of tenants and benefits from long-term leases (typically 5–10 years), inflation-linked rents, and low vacancy rates in core areas. These features make it attractive to investors seeking both income stability and capital appreciation.
Market Performance: Lisbon, Porto, and Beyond
Lisbon
As Portugal’s most established retail market, Lisbon offers liquidity, international visibility, and high rents. Key zones include:
- Avenida da Liberdade: Prime rents range from €100–€140/m²/month, with yields around 4.5–5.0%. The street hosts luxury brands like Louis Vuitton and Cartier.
- Baixa-Chiado & Rua Augusta: These pedestrian-heavy areas see foot traffic of up to 90,000 people per day in peak season.
- Emerging neighborhoods like Príncipe Real cater to lifestyle and concept retail, supported by municipal redevelopment initiatives.
Porto
Porto’s high-street retail sector is fast maturing. It combines strong tourism momentum with lower acquisition costs:
- Rua de Santa Catarina: Prime rents at €55–€80/m²/month with high pedestrian volumes (~60,000/day).
- Avenida dos Aliados: Increasingly attractive for flagship and experiential tenants.
- Miguel Bombarda District: A niche area gaining traction with investors targeting cultural or boutique retail concepts.
Secondary Cities
Investors are expanding into cities like Braga and Faro due to growing populations and infrastructure upgrades:
- Braga: Home to a large student population and rising tech sector, offering yields of 6.0–6.5%.
- Faro: Seasonal retail linked to luxury tourism, especially in food and beverage (F&B).
- Coimbra: Student-driven economy with strong local demand for services and affordable retail.
Demand Drivers: Footfall, Tourism, and Tenant Diversification
Portugal welcomed over 31 million tourists in 2024, boosting demand in urban retail corridors. In Lisbon, tourist spending accounts for 30–40% of retail transactions in the city center.
Tenant demand is also evolving. According to CBRE, 37% of new high-street leases in 2023 were signed by food and beverage operators. The trend reflects a broader shift from traditional retail toward experiential, service-based tenants — from specialty cafes and coworking hybrids to boutique gyms and concept stores.
High occupancy rates reinforce these trends:
- Lisbon’s top retail corridors report >92% occupancy.
- Porto’s central zones hold at ~90%.
- Secondary cities are seeing 10–15% vacancy, but this is declining with targeted development.
Rental Yields and Lease Characteristics
Street retail properties in Portugal offer competitive gross yields, depending on location:
| Location | Prime Rent (€/m²/month) | Average Yield (%) |
| Lisbon | €100–€140 | 4.5%–5.0% |
| Porto | €55–€80 | 5.0%–5.5% |
| Secondary Cities | €25–€45 | 5.5%–6.5% |
Leases in core locations are often index-linked to inflation and include maintenance costs under NNN (triple net) structures. Tenants are increasingly international brands or lifestyle operators, reducing credit risk.
Risk Considerations
While the fundamentals are strong, investors must evaluate several key risks:
- Tourism dependence: Overexposure to tourism-heavy districts can create seasonal volatility.
- Regulatory limitations: Heritage protections or zoning rules may restrict renovation or use changes.
- E-commerce displacement: Traditional retailers remain vulnerable; however, experiential and F&B tenants are more resilient.
- Inflation & interest rates: Portugal’s borrowing rates remain elevated (~4.2% in 2025), which may compress returns if not factored into acquisition models.
Due diligence, especially regarding licensing, tenant covenants, and location-level foot traffic, is essential to mitigate these risks.
Strategic Outlook: Consumer Trends and Design Adaptation
Today’s consumers seek more than just products — they look for interaction, authenticity, and experience. According to Savills, nearly 70% of Portuguese urban consumers now prefer to shop within walking distance of home. This supports the street retail model, particularly in residential-heavy areas.
Emerging tenant needs are influencing property selection:
- Smaller, adaptable spaces that support hybrid usage.
- Architectural authenticity, especially in historic buildings.
- Outdoor integration (e.g., sidewalk seating, retractable façades).
- Tech-readiness (QR menus, smart checkout, etc.).
This consumer evolution expands the investible universe of street retail and aligns with ESG and community-oriented investment strategies.
Conclusion: A Resilient and High-Potential Asset Class
Street retail in Portugal offers a compelling case for commercial real estate investors. It combines income-generating potential with defensive characteristics in a shifting retail environment.
Key strengths include:
- Rental yields between 4.5% and 6.5%
- High occupancy in Lisbon and Porto
- Rising tenant diversity and lifestyle alignment
- Stable tourist inflow and growing urban populations
- Long-term support from public infrastructure investment
As Portugal’s urban retail sector matures, investors who align with foot traffic trends, consumer behavior, and neighborhood revitalization stand to benefit most. Street retail is no longer just a legacy asset — it’s a forward-looking investment opportunity with strong fundamentals and growing global appeal.

